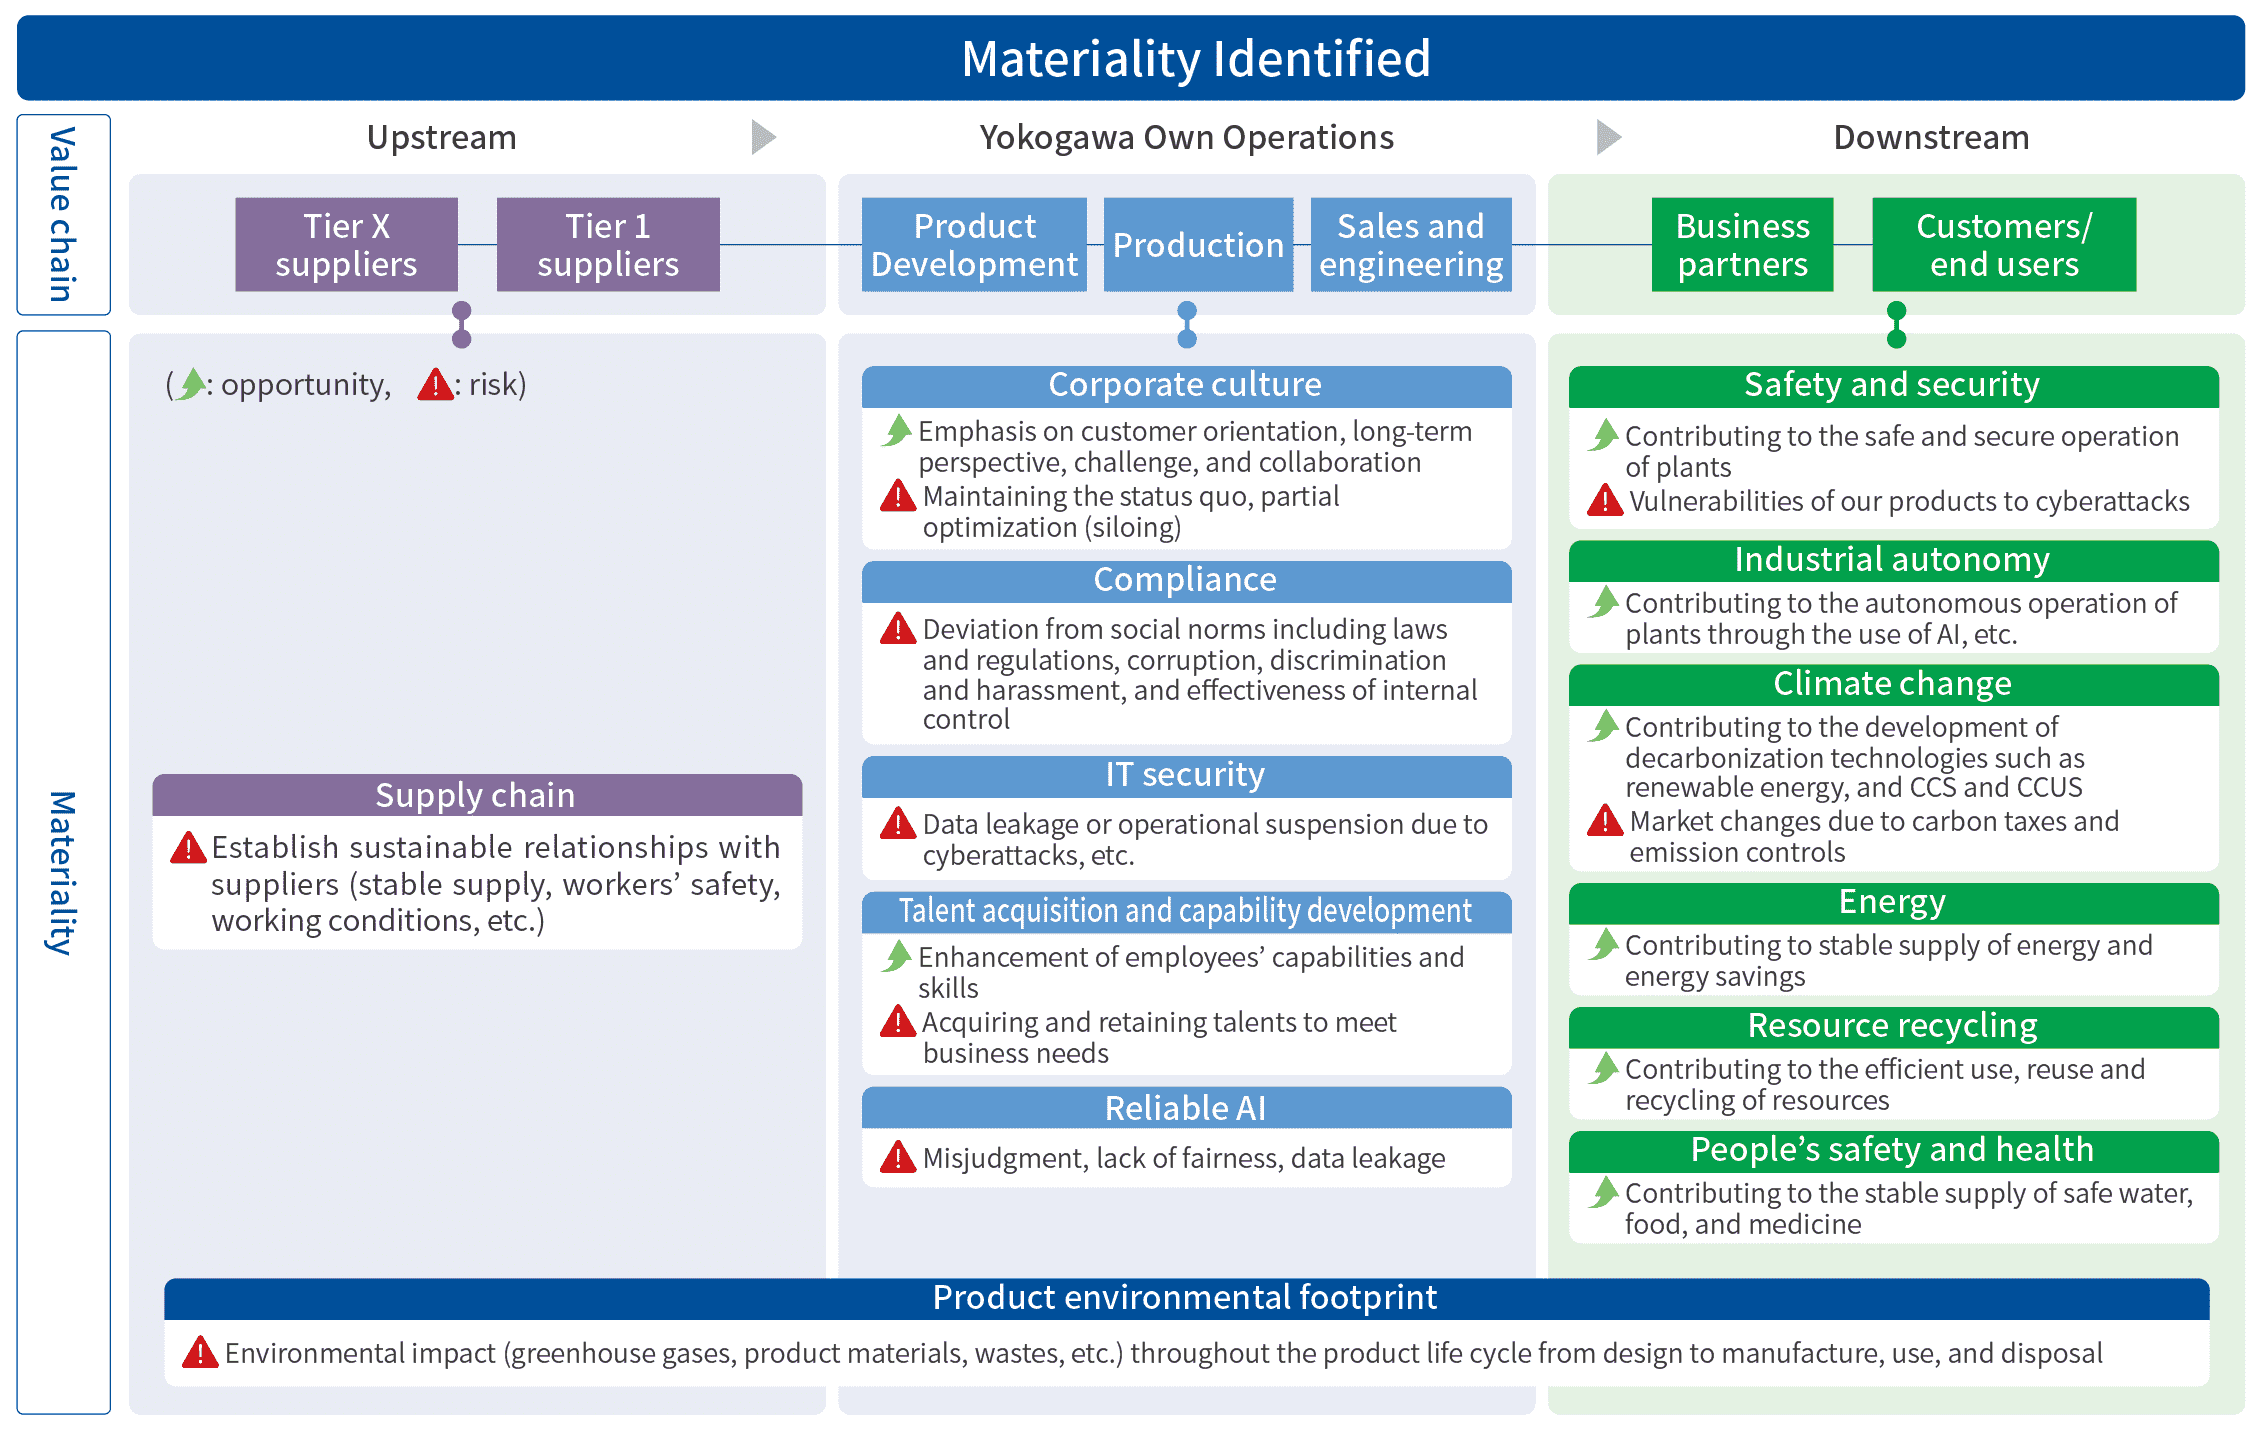
Yokogawa identifies materiality based on the concept of double materiality adopted by the Global Reporting Initiative (GRI) and European standards. We make assessment in terms of the “social and environmental impact” and the “financial impact on the Group,” and formalize materiality after discussions at the Sustainability Committee and report it to the Board of Directors. The materiality is reviewed in conjunction with the business strategies of the GS2028 medium-term business plan.
Process of Materiality Analysis
|
Step 1 |
Understand the value chain and list sustainability issues relevant to our business* * Referring to the ESRS (European Sustainability Reporting Standards). |
|---|---|
|
Step 2 |
Assess items listed in step 1 based on the following two axes
|
|
Step 3 |
Based on the input from stakeholders, organize the assessment result in step 2,and have discussion at the Sustainability Committee |
|
Step 4 |
Identify items assessed as highly material as a result of assessment as materiality |
|
Step 5 |
Confirm the consistency of materiality and six contribution areas |
Discussion and review by the executives
The results of the materiality analysis are reviewed annually by the Sustainability Committee.
At the Sustainability Committee held in July 2026, the granularity and assessment result of materiality were adjusted based on inputs obtained through stakeholder engagement, including customer satisfaction surveys, dialogues with investors, and external ESG evaluations.
Furthermore, group discussions were held by the executives, where the importance for Yokogawa from the perspective of opportunities and risks was actively discussed. In addition to re-emphasizing the significance of “safety and security,” “corporate culture,” “compliance,” “IT security,” “talent acquisition and capability development,” and “supply chains,” we added “reliable AI,” “industrial autonomy,” and “product environmental footprint” to materiality.
We have confirmed that materiality reviewed this time is consistent with the six contribution areas.
* Referring to the ESRS (European Sustainability Reporting Standards).
Materiality Identified